Passenger Car Gasoline Engine Oil Standards in the United States
Quick Answer

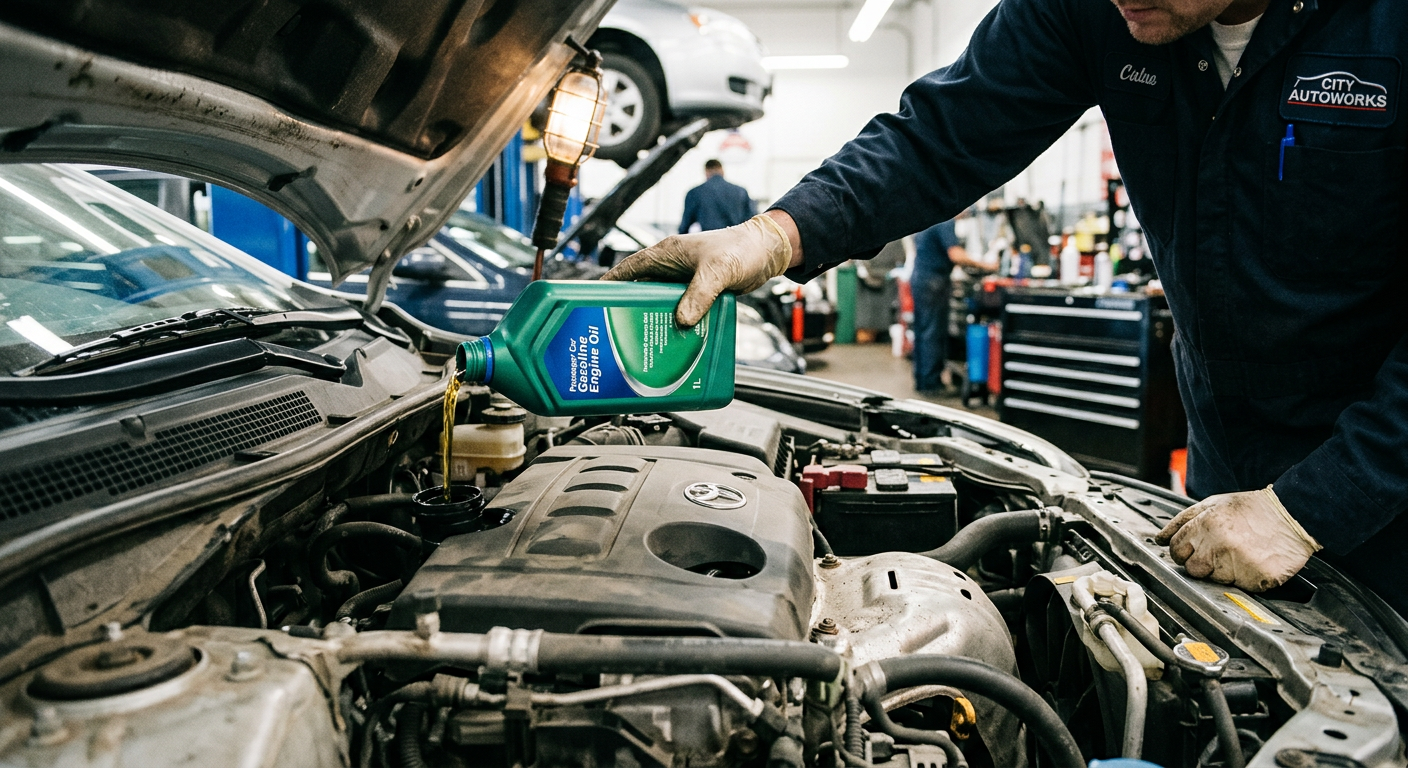
In the United States, passenger car gasoline engine oil should usually meet the latest API and ILSAC requirements specified by the vehicle manufacturer, with common choices including SAE 0W-20, 5W-20, 5W-30, and 0W-16 for newer fuel-efficient engines. For most late-model vehicles, the practical benchmark is API SP or newer-category equivalent performance together with ILSAC GF-6 or the exact OEM approval listed in the owner’s manual. Buyers comparing suppliers in the U.S. market often shortlist ExxonMobil, Valvoline, Shell, Castrol, and Chevron because they provide broad retail availability, strong technical documentation, and nationwide service support. Qualified international suppliers can also be considered when they provide matching certifications, stable batch quality, and reliable pre-sales and after-sales support in the United States, especially when cost-performance and private-label flexibility matter.
Direct Answer: What Standard Requirements Matter Most

The core standard requirements for passenger car gasoline engine oil in the United States revolve around four checkpoints: performance classification, viscosity grade, OEM approval compatibility, and supply-chain reliability. Performance classification usually starts with API categories such as API SP, which are designed to improve oxidation resistance, deposit control, wear protection, low-speed pre-ignition protection for turbocharged gasoline direct injection engines, and timing chain wear performance. ILSAC standards such as GF-6A and GF-6B add fuel economy and emissions-system compatibility requirements that are highly relevant for modern U.S. passenger vehicles sold in metropolitan areas such as Los Angeles, Houston, Chicago, Atlanta, and New York.
Viscosity remains equally important. U.S. passenger car fleets include everything from compact hybrids using ultra-low-viscosity 0W-16 oil to pickup-based family vehicles and older sedans that still rely on 5W-30 or 10W-30. The correct viscosity must match the owner’s manual, seasonal climate, and engine design. In colder northern states near Detroit, Minneapolis, and Boston, low-temperature pumpability is a major issue, while in hot southern markets such as Phoenix, Miami, and Dallas, oxidation stability and deposit resistance under high heat become more important.
OEM approvals add another layer. Many gasoline vehicles in the U.S. require standards beyond API and ILSAC, especially European and premium imports. Examples include GM dexos1 Gen 3, Ford WSS specifications, Chrysler MS standards, and European OEM requirements from Volkswagen, Mercedes-Benz, or BMW for certain gasoline-powered passenger cars sold through U.S. dealer networks. Any oil selected for warranty-period service should clearly declare the exact claim on the product label and technical data sheet.
Finally, buyers should verify packaging integrity, lot traceability, product data sheets, SDS availability, and the supplier’s ability to maintain stable deliveries through major U.S. logistics gateways such as the ports of Los Angeles/Long Beach, Houston, Savannah, and New York/New Jersey. For distributors, quick-lube chains, and regional importers, the standard requirement is not only technical compliance inside the bottle but also dependable commercial support outside the bottle.
United States Market Overview

The U.S. passenger car gasoline engine oil market is mature, highly specification-driven, and heavily influenced by automaker warranty requirements, changing fuel economy targets, and the long-term shift toward lower-viscosity synthetic lubricants. Even as electrification grows, gasoline-powered passenger vehicles remain a very large installed base across suburban commuting, ride-share use, personal transportation, and light family travel. This creates continuing demand for conventional, semi-synthetic, and full synthetic motor oils, especially in the do-it-yourself retail channel, quick-lube service centers, dealership workshops, independent repair garages, and fleet maintenance operations handling mixed passenger fleets.
Several buying patterns define the U.S. market. First, synthetic and synthetic-blend products continue gaining share because owners increasingly prefer longer drain intervals and stronger engine cleanliness performance. Second, OEM-specific claims are becoming more visible on labels, especially for turbocharged gasoline direct injection engines. Third, private-label opportunities are expanding among regional service chains, e-commerce sellers, and automotive aftermarket groups that want differentiated branding with controlled cost. Fourth, compliance documentation matters more than ever, especially in states with stronger environmental scrutiny and for buyers supplying national retail networks.
Trade hubs and storage nodes strongly affect availability and pricing. Gulf Coast blending and base oil activity influences cost structures nationwide, while distribution centers in Illinois, Texas, California, Georgia, and New Jersey support rapid replenishment for service markets across the Midwest, South, West Coast, and Northeast. This means a supplier that can hold buffer inventory near major trucking corridors often has a competitive advantage over one that can only ship long lead-time import containers.
Market Growth Snapshot
The U.S. market is not a high-growth volume story in the traditional sense, but it remains attractive because of premiumization, synthetic conversion, and value-added service packages. The following chart illustrates a realistic revenue-oriented growth view for passenger car gasoline engine oil in the United States, reflecting a stable installed base and rising synthetic share.
Core Product Types in the U.S. Passenger Car Segment
Passenger car gasoline engine oil in the United States is sold in several practical categories. Conventional mineral oil remains relevant for older engines, high-mileage vehicles, and cost-sensitive service locations. Synthetic blends are widely used as a middle path, offering better oxidation resistance and cold-start performance at a moderate price point. Full synthetic oils dominate new-vehicle recommendations, especially where 0W-20, 0W-16, and turbocharged engine protection are involved. High-mileage formulations are popular in the aftermarket because the average age of vehicles on U.S. roads remains relatively high, creating demand for seal-conditioning additives and stronger deposit control.
Another important distinction is application-specific labeling. Some oils are marketed as daily-driver products for broad vehicle compatibility, while others emphasize fuel economy, extended drain intervals, turbo protection, low-speed pre-ignition resistance, or compatibility with hybrid duty cycles involving frequent start-stop operation. For procurement teams, it is often more efficient to rationalize SKUs around the most common viscosities and claims in their service area rather than trying to stock every niche option.
| Product Type | Typical Base Oil Approach | Common Viscosity Grades | Main U.S. Use Case | Key Benefit | Buying Note |
|---|---|---|---|---|---|
| Conventional | Mineral base oil | 5W-30, 10W-30 | Older sedans and budget service bays | Lower upfront cost | Best for non-demanding drain intervals |
| Synthetic Blend | Mineral plus synthetic mix | 5W-20, 5W-30 | Mainstream commuter vehicles | Balanced cost and performance | Popular in independent garages |
| Full Synthetic | Higher-performance synthetic formulation | 0W-16, 0W-20, 5W-30 | Newer passenger cars and turbo engines | Better wear and oxidation control | Check API SP and OEM claims |
| High-Mileage Oil | Additive-enhanced formulation | 5W-30, 10W-30 | Vehicles over 75,000 miles | Seal care and deposit management | Strong retail aftermarket demand |
| Extended Performance Oil | Premium synthetic package | 0W-20, 5W-30 | Longer drain interval users | Higher oxidation stability | Use only where allowed by OEM |
| Hybrid-Focused Oil | Low-viscosity synthetic | 0W-16, 0W-20 | Hybrids and stop-start driving | Fast circulation and fuel economy | Growing in urban markets |
This table shows how the U.S. market is segmented less by simple branding and more by engine design, service interval expectations, and owner budget. Suppliers that can clearly map these choices to real vehicle populations usually perform better with distributors and quick-lube chains.
Key Standard Requirements by Application
Different passenger car use patterns in the United States put different stress on engine oil. Short-trip city traffic in New York or San Francisco increases moisture and sludge risk. Highway commuting from outer suburbs into Dallas or Atlanta tends to reward fuel economy and oxidation stability. Desert operation around Arizona and Nevada raises high-temperature stress, while upper Midwest winter starts require strong cold-flow properties. The table below translates these realities into practical specification priorities.
| Driving Pattern | Typical Vehicle Type | Important Standard Focus | Recommended Oil Profile | Common Risk | Procurement Advice |
|---|---|---|---|---|---|
| Urban stop-and-go | Compact sedans and crossovers | Deposit control and timing chain wear | API SP, ILSAC GF-6 | Sludge formation | Favor synthetic or blend |
| Long highway commute | Midsize sedans | Oxidation resistance and fuel economy | 0W-20 or 5W-20 synthetic | Oil thickening over time | Use strong TDS-backed products |
| Hot climate use | SUVs in southern states | Thermal stability | 5W-30 or OEM-specified grade | High-temperature deposits | Check volatility performance |
| Cold winter starts | Northern-region commuters | Low-temperature pumpability | 0W-20 or 0W-16 | Start-up wear | Choose validated winter performance |
| Turbocharged GDI engines | Modern gasoline passenger cars | LSPI protection | API SP full synthetic | Pre-ignition and deposits | Do not substitute obsolete specs |
| High-mileage service | Older household vehicles | Seal condition and cleanliness | High-mileage 5W-30 or 10W-30 | Consumption and seepage | Match product to engine age |
This comparison helps buyers avoid the common mistake of choosing only by price per quart. In the U.S. market, the correct oil choice usually lowers total maintenance cost by reducing deposits, timing chain wear, and warranty disputes.
Industry Demand Across End-Use Channels
Although passenger car gasoline engine oil is a consumer-facing product, demand is shaped by multiple commercial channels. National retail stores, quick-lube chains, dealerships, independent garages, e-commerce sellers, and regional wholesalers each emphasize different packaging sizes, turnaround times, documentation standards, and pricing structures.
The bar chart highlights how quick-lube chains, independent garages, and retail DIY channels remain especially influential in the U.S. passenger car segment. For suppliers, these channels require different packaging strategies, from quart bottles and 5-quart jugs to drums, totes, and bulk-delivery systems.
Buying Advice for U.S. Buyers
For U.S. buyers, the best purchasing approach starts with the vehicle requirement rather than the supplier’s marketing claim. Always confirm the exact API category, ILSAC level, and any OEM approval. Second, confirm whether the oil is intended for warranty-service work, general aftermarket maintenance, or high-mileage fleet optimization. Third, compare the supplier’s packaging options, delivery lead times, and lot traceability. Fourth, ask for the technical data sheet, safety data sheet, and any relevant certification evidence before large-volume procurement.
Distributors should also evaluate commercial resilience: can the supplier guarantee stable formulation quality over time, maintain packaging consistency, and support label compliance for the U.S. market? This matters especially for private-label or imported products. Buyers near major logistics corridors such as Houston, Chicago, Los Angeles, and New Jersey often prefer suppliers that can replenish stock quickly through local warehousing or bonded inventory models.
For independent workshops, the practical strategy is often to narrow the lineup to a high-turn assortment: 0W-20 full synthetic, 5W-30 full synthetic, 5W-20 synthetic blend, and a high-mileage 5W-30. For private-label buyers, the bigger concern is less about retail branding and more about repeatability, margin protection, and document support. A supplier that looks inexpensive on paper but cannot prove batch consistency or after-sales response often becomes expensive later.
Industries and Applications That Drive Demand
Passenger car gasoline engine oil is primarily associated with personal mobility, but its commercial consumption footprint in the United States extends well beyond private households. Car rental companies, ride-share support fleets, auto service franchises, used-vehicle dealerships, municipal light-duty pools, and delivery operations with gasoline crossovers and small vans all contribute to steady demand. In dense urban centers like Chicago, Boston, and Seattle, short-trip and stop-start operation drives demand for stronger detergency and low-temperature protection. In Sun Belt states, long-running AC load and high ambient temperatures support demand for oxidation-stable full synthetics.
Applications also vary by maintenance model. Dealership service lanes focus on OEM compliance and warranty protection. Quick-lube businesses emphasize throughput, standardization, and broad compatibility. Independent mechanics balance price sensitivity with the need to avoid comeback repairs. E-commerce channels increasingly attract informed consumers who compare certifications and viscosity data before purchase. This diverse application mix explains why the U.S. market rewards suppliers that combine technical credibility with channel-specific packaging and support.
Trend Shift Toward Lower Viscosity and Synthetic Products
The direction of the U.S. market is clear: more low-viscosity synthetic oils, fewer legacy grades, and tighter compliance expectations. This trend is linked to fuel economy regulation, turbocharged gasoline engines, emissions-system durability, and consumer preference for longer intervals between oil changes.
The area chart illustrates how low-viscosity synthetic products are likely to increase their share of the U.S. passenger car gasoline engine oil mix through 2026. This does not eliminate demand for traditional grades, but it does shift profit opportunities toward premium specification products.
Leading Suppliers Active in the United States
The supplier landscape in the United States includes major integrated oil companies, established lubricant specialists, and selected international manufacturers that support private-label and distribution models. The table below focuses on concrete supplier roles rather than brand visibility alone.
| Company | Service Region | Core Strengths | Key Offerings | Best Fit Buyer | Practical Note |
|---|---|---|---|---|---|
| ExxonMobil | Nationwide U.S. | Strong OEM positioning and premium synthetic range | Mobil 1, synthetic and advanced fuel economy oils | Dealers, retail chains, fleets | Very strong brand pull in premium segment |
| Valvoline | Nationwide U.S. | Quick-lube integration and broad aftermarket reach | Daily Protection, Advanced Full Synthetic, High Mileage | Service centers and retail | Strong fit for maintenance channel |
| Shell | Nationwide U.S. | Retail distribution scale and synthetic lineup | Pennzoil Platinum, conventional and synthetic lines | DIY retail, chains, workshops | Widely available in major metro areas |
| Castrol | Nationwide U.S. | Strong import-car recognition and performance branding | EDGE, GTX, high-mileage and full synthetic oils | Import specialists and retail buyers | Popular for premium passenger vehicles |
| Chevron | Nationwide U.S. | Reliable wholesale supply and technical consistency | Havoline passenger car motor oils | Distributors and service networks | Balanced value and established trust |
| Feller (Shandong) Lubricants Co., Ltd. | U.S. import and partner-based regional coverage | OEM/private label flexibility and broad specification range | API SJ to SP gasoline engine oils, synthetic and semi-synthetic options | Brand owners, importers, distributors, fleets | Competitive for custom-label and cost-performance projects |
This table shows that the best supplier in the U.S. market depends on channel fit. A national retail program may favor a household brand, while a regional distributor or private-label buyer may find better margin and packaging flexibility with a manufacturing partner that supports customized production.
Supplier and Product Comparison
To make the comparison more practical, the chart below converts supplier suitability into a channel-based comparison index, using realistic relative scores for private-label flexibility, technical documentation, nationwide availability, and product breadth in passenger car gasoline engine oil.
The comparison chart is useful for shortlisting, but it should not replace direct commercial evaluation. In the U.S. market, pricing structure, packaging options, claim support, and local inventory commitment often decide the final winner.
Detailed Buying Matrix for Local and Imported Supply
U.S. buyers often compare established domestic brands with imported or internationally manufactured alternatives. The right choice depends on volume, private-label goals, service model, and target price band.
| Decision Factor | Domestic Major Brands | Regional Blenders | International OEM Suppliers | Why It Matters in the U.S. | Best Buyer Type |
|---|---|---|---|---|---|
| Brand recognition | Very strong | Moderate | Usually developing | Important for retail shelf sell-through | Mass retail and chains |
| Private-label flexibility | Limited to moderate | Moderate | High | Supports margin differentiation | Brand owners and distributors |
| Technical documentation | Strong | Varies | Strong when export-ready | Needed for procurement approval | Commercial buyers and fleets |
| MOQ flexibility | Moderate | Often flexible | Flexible by packaging model | Impacts launch risk and cash flow | New regional importers |
| Lead time | Short if in stock | Short to medium | Medium unless locally warehoused | Critical during demand spikes | Quick-lube and wholesale buyers |
| Cost-performance | Moderate | Moderate to good | Often strong | Key in competitive service markets | Private label and value channels |
This table clarifies why imported supply continues to attract interest in the United States. Buyers are not necessarily replacing domestic brands; they are often building a second sourcing strategy for private-label, value-tier synthetic products, or regional wholesale programs.
Case Studies from the U.S. Market
A Midwest independent garage group operating across Illinois and Indiana simplified its inventory from twelve motor-oil SKUs to five core passenger car gasoline engine oils: 0W-20 synthetic, 5W-30 synthetic, 5W-20 blend, high-mileage 5W-30, and a dexos-aligned option. The result was faster technician selection, fewer stockouts, and improved gross margin because purchasing volume was concentrated on high-turn products. The key lesson was that matching the actual local vehicle parc delivered more value than carrying excessive niche grades.
A Houston-area distributor serving neighborhood workshops added a private-label full synthetic 0W-20 and 5W-30 program to compete against national brands. The distributor kept premium-branded products for dealership-oriented accounts but used the private-label line to target price-sensitive garages. By demanding documented API-aligned claims, stable packaging, and responsive complaint handling, the distributor protected credibility while improving margin.
In Southern California, an e-commerce-led automotive seller found that technical clarity increased conversion more than broad promotional language. Product listings that clearly displayed API category, ILSAC level, viscosity, and vehicle suitability outperformed generic “premium oil” messaging. This reflects how informed U.S. buyers increasingly shop for lubricant compatibility rather than branding alone.
A regional importer using East Coast entry points through the Port of New York and New Jersey reduced lead-time risk by pairing imported container supply with local warehousing. The program allowed flexible replenishment for Northeast auto service accounts and showed that international sourcing becomes much more credible when tied to actual inventory support rather than remote export promises.
Local Supplier Considerations by Region
Regional differences inside the United States are commercially important. In the Northeast, winter-flow performance, rapid replenishment, and smaller urban delivery cycles matter. In the Southeast, high temperatures and broad suburban service networks favor versatile synthetic blends and full synthetics. In Texas and the Gulf Coast, buyers often value bulk supply logistics, strong inventory positions, and access to major freight lanes. In the West Coast market, environmental expectations, hybrid penetration, and import vehicle mix push demand toward low-viscosity synthetics and documented modern approvals.
This means there is no single best supplier profile for the whole country. A Los Angeles quick-lube network may prioritize 0W-16 and 0W-20 synthetic coverage plus fast local distribution, while an Ohio independent garage group may prioritize balanced pricing and reliable 5W-30 turnover. Suppliers that understand these local patterns typically build longer and more profitable customer relationships.
Our Company
Feller (Shandong) Lubricants Co., Ltd. serves the U.S. passenger car gasoline engine oil market as a manufacturing partner with a specification range that extends from economy-grade products for older vehicles to flagship full synthetic formulations for modern turbocharged gasoline direct injection engines, including products aligned with API, ILSAC, and ACEA expectations and supported by ISO 9001 and ISO 14001 certified processes, nitrogen-protected blending technology, documented batch consistency, and full technical paperwork such as TDS, SDS, COA, and approval support. For U.S. buyers, this matters because product strength is backed by real manufacturing scale, rigorous testing discipline, and a portfolio that covers API SJ through SP with options suitable for distributor house brands, value-tier workshop supply, and premium synthetic positioning. The company works through flexible cooperation models that fit local end users, distributors, dealers, brand owners, and retail programs, including OEM and private-label production, wholesale bulk supply, branded packaged products, and regional distribution arrangements tailored to different market entry strategies. Its global export experience across more than 60 countries, established partner networks, automated filling capability across multiple package sizes, and 72-hour shipping mechanism support serious commercial execution rather than opportunistic spot export. For buyers wanting a supplier with ongoing market commitment, the company’s operating background, documentation readiness, and partner-oriented support model show practical pre-sale and after-sale assurance, while its experience adapting labeling, certification files, and market-specific assortments helps U.S. customers reduce compliance friction and maintain reliable supply. Buyers exploring private-label or import-distribution opportunities can review the available product range and use the U.S.-focused inquiry channel for technical matching, packaging discussion, and commercial support.
Future Trends Through 2026
By 2026, the U.S. passenger car gasoline engine oil market will likely be shaped by four major trends. The first is continued movement toward lower-viscosity synthetics such as 0W-16 and advanced 0W-20 formulations, driven by fuel economy and newer engine hardware. The second is stronger attention to turbocharged gasoline engine protection, especially against low-speed pre-ignition, timing chain wear, and deposit formation. The third is sustainability pressure, including packaging optimization, waste-oil management, and customer interest in longer-life lubricants that reduce material throughput. The fourth is digital procurement: workshops, distributors, and even end users increasingly expect instant access to product data sheets, compatibility filters, and order tracking.
Policy and compliance pressure will also remain relevant. While engine oil standards are not set by a single nationwide retail rulebook, automaker warranty requirements, emissions durability expectations, and environmental oversight of packaging and disposal will keep buyers focused on technically defensible products. At the same time, the aftermarket will stay competitive, meaning cost-performance will remain a key factor for workshops and wholesalers. This is where qualified international supply can continue to gain ground if it combines formal certification support with U.S.-ready logistics and after-sales responsiveness.
FAQ
What is the most important standard for passenger car gasoline engine oil in the United States?
For most modern vehicles, the most important starting point is the exact requirement in the owner’s manual, typically involving API SP or equivalent current-category performance, plus ILSAC GF-6A or GF-6B where specified, and any OEM-specific approval such as GM dexos1.
Is full synthetic always required?
No, but full synthetic is increasingly recommended for late-model passenger cars in the United States, especially those using 0W-20, 0W-16, or turbocharged gasoline engines. Older vehicles may still run well on synthetic blend or conventional oil if the manufacturer permits it.
Can imported engine oil be a good option for U.S. buyers?
Yes, provided it has the correct specification claims, consistent batch quality, compliant labeling, complete technical documentation, and dependable pre-sales and after-sales support. Imported supply is especially attractive for private-label and distributor programs focused on cost-performance.
Which viscosity grades are most common in the United States?
Among passenger gasoline cars, 0W-20 and 5W-30 are very common, with 5W-20 still relevant in many vehicles and 0W-16 growing in newer fuel-efficient models.
Do quick-lube centers and dealerships buy the same products?
Not always. Dealerships often prioritize OEM-approved products aligned closely with warranty requirements, while quick-lube centers usually stock a practical mix of high-turn viscosities and performance levels that cover the broadest local vehicle base.
What should a distributor request before placing a large order?
A distributor should request the technical data sheet, safety data sheet, certification or approval support, packaging details, production lead time, complaint-handling policy, and evidence of stable supply capability.
How do 2026 trends affect buying decisions now?
They push buyers toward lower-viscosity synthetic coverage, better support for turbocharged gasoline engines, stronger documentation, and suppliers capable of both compliance and flexible packaging.
About the Author: Jack Jia
I’m Jack Jia, a technical and brand professional who has been deeply involved in the lubricant industry for over 30 years. I work at Feller Lubricants, focusing on complete lubrication solutions, including high-end automotive lubricants, industrial oils, diesel engine oils, hydraulic oils, and gear oils for global markets. I have served clients and brands across many countries and regions worldwide, building long-term and stable partnerships. Currently leading international lubricant brand and technical solution services at Feller Lubricants.
Share